A overview to jewelry insurance coverage for valuable items ?
Quick Answer
Jewelry insurance for valuable items is a specialized policy that financially protects your fine jewelry against theft, loss, or damage. Unlike standard homeowners insurance, it covers the full appraised value worldwide, ensuring that your high-value pieces and any unique personalized keepsake are completely protected.
What is personalized keepsake in relation to A overview to jewelry insurance coverage for valuable items ??
Key Takeaway: A personalized keepsake represents a uniquely customized piece of jewelry that holds immense emotional value, requiring specialized insurance coverage to guarantee its full financial replacement value in the event of an unforeseen loss or damage.
Welcome to the ultimate, comprehensive guide on jewelry insurance coverage for your most valuable items. Whether you have recently become engaged, inherited a family heirloom, or purchased a beautiful personalized keepsake, protecting your precious jewelry is an essential step in responsible ownership. Jewelry is more than just metal and stone; it is a physical manifestation of our memories, relationships, and milestones. However, because these items are small, highly valuable, and easily lost or stolen, they face unique risks that standard property insurance often fails to adequately cover.
In this extensive overview, we will walk through every single aspect of jewelry insurance. We will explore what constitutes a valuable item, why standard home insurance isn’t enough, how to get an accurate appraisal, and exactly how to choose the right policy. Our goal is to provide you with all the information you need to make an educated decision about safeguarding your treasures.
First, let us define what we mean by valuable items in the context of insurance. Valuable items typically include engagement rings, wedding bands, luxury watches, high-end necklaces, and specifically, any personalized keepsake that holds significant financial or sentimental value. Standard homeowners, renters, or condo insurance policies offer coverage for personal property, but this coverage is notoriously limited when it comes to jewelry. Most standard policies will cap jewelry coverage at a very low limit—often between $1,000 and $2,000. If a $10,000 diamond ring is stolen from your home, your standard home insurance will only pay out the capped amount, leaving you to cover the remaining $8,000 out of pocket. Furthermore, standard policies usually only cover specific “named perils,” such as fire or theft. If you accidentally drop your ring down the sink drain or lose it while swimming at the beach, a standard policy will not pay a dime.
This is where specialized jewelry insurance, often called a “personal articles floater” or an inland marine policy, becomes completely vital. Jewelry insurance is specifically designed to fill the gaps left by standard property insurance. It provides comprehensive “all-risk” coverage. This means that the policy protects your valuable items against any type of loss, unless specifically excluded in the contract. Whether your jewelry is stolen from a hotel room, falls off your finger while you are hiking, or suffers a chipped diamond from hitting it against a countertop, specialized jewelry insurance will cover the repair or replacement.
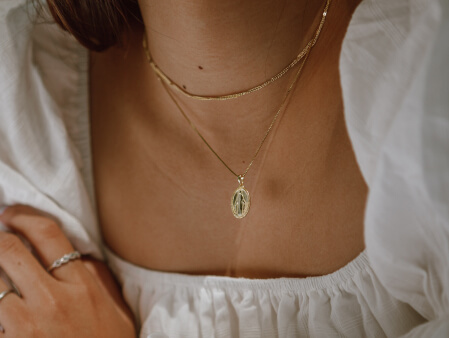
Now, let us discuss the emotional core of this topic: the personalized keepsake. In the modern era of jewelry, customization is incredibly popular. People want pieces that tell their unique story. A personalized keepsake could be a custom name necklace featuring the names of your children, a birthstone ring commemorating a special date, or a locket containing a tiny photograph. From a business like JewelryAll, which specializes in custom name necklaces, rings, and bracelets, these pieces are crafted with care and precision. But how does insurance view a personalized keepsake?
The tricky thing about insuring a personalized keepsake is that while the financial value can be calculated based on materials (gold, silver, diamonds), the sentimental value is irreplaceable. If a standard gold chain is stolen, the insurance company can easily buy you a new standard gold chain. But if a custom-engraved bracelet with a unique message is lost, it cannot simply be bought off a shelf. When you insure a personalized keepsake, the insurance company must agree to replace the item exactly as it was. This means they will have to pay a jeweler to recreate the custom design, re-engrave the special message, and source the exact same materials. This requires what is known in the insurance world as an “agreed value” policy or a policy that guarantees replacement with “like kind and quality.” It is crucial to ensure your policy specifically covers the custom craftsmanship involved in recreating a personalized keepsake.
How do you actually get jewelry insurance? The process is surprisingly straightforward, but it requires careful attention to detail. The very first step is obtaining a professional appraisal. Do not skip this step, and do not rely solely on the retail receipt. While a receipt shows what you paid, the market value of gold, silver, and diamonds fluctuates constantly. An appraisal from a certified gemologist or an appraiser affiliated with a recognized organization (like the Gemological Institute of America or the American Gem Society) provides an objective valuation of the piece. The appraiser will examine the carat weight, cut, color, and clarity of any gemstones, as well as the weight and purity of the metals. For a personalized keepsake, the appraiser will also factor in the cost of the custom design work. You should keep this appraisal updated every two to three years to ensure your coverage limits keep pace with inflation and rising precious metal prices.
Once you have your appraisal in hand, you have two main avenues for obtaining insurance. The first option is to add a “rider” or “endorsement” to your existing homeowners or renters insurance policy. This is often the most convenient and cost-effective route. The second option is to purchase a standalone policy from a company that specializes exclusively in jewelry insurance, such as Jewelers Mutual or Chubb. Standalone policies often provide more robust coverage and have fewer hoops to jump through if you need to file a claim.
What should you look for in a jewelry insurance policy? You need to read the fine print carefully. The most important clause to look for is the settlement option. There are generally three ways an insurer will settle a claim:
1. Replacement Value: The insurance company pays you the full amount it would cost to replace the item at current market prices, up to the limit stated on the policy.
2. Actual Cash Value: The insurer pays the replacement cost minus depreciation. This is rarely used for fine jewelry but is something to watch out for.
3. Agreed Value: You and the insurance company agree on the value of the item when the policy is written. If the item is lost, you receive that exact dollar amount, regardless of market fluctuations. For high-end custom pieces or a unique personalized keepsake, an agreed value policy is almost always the safest bet.
Another crucial aspect to look for is “mysterious disappearance” coverage. This is the industry term for losing an item without knowing exactly how or where it happened. If you take off your ring at a public restroom sink and walk away without it, that is a mysterious disappearance. Because standard home insurance requires proof of a specific event (like a forced-entry theft), mysterious disappearance is not covered. A good jewelry insurance policy, however, will explicitly include mysterious disappearance.
Let us talk about the cost of jewelry insurance. Generally, jewelry insurance costs between 1% and 2% of the item’s total appraised value per year. This means that if you have a ring appraised at $5,000, your annual premium will likely be somewhere between $50 and $100. Several factors can influence your specific rate. Your geographic location plays a huge role; if you live in an area with high crime rates, your premiums will be higher. Your deductible—the amount you pay out of pocket before insurance kicks in—also affects your premium. Choosing a higher deductible will lower your annual premium, but it means you will pay more if you ever need to file a claim. Some insurers also offer discounts if you store your jewelry in a high-security home safe or a bank safety deposit box when you are not wearing it.
Filing a claim is a process that no one wants to go through, but it is essential to understand how it works. If your jewelry is lost, stolen, or damaged, you must contact your insurance company immediately. You will be asked to provide a copy of the appraisal, any photographs you have of the item, and a police report if the item was stolen. It is highly recommended to take detailed, high-resolution photos of all your valuable jewelry from multiple angles, capturing any unique engravings or flaws. Store these photos in a secure cloud service alongside digital copies of your appraisals. Once the claim is filed, an adjuster will review the details. If the claim is approved, the insurance company will either issue you a check for the agreed amount, require you to work with a specific partner jeweler to replace the piece, or reimburse you for the cost of repairs. If your piece was a personalized keepsake, you may need to work closely with the adjuster and a jeweler (perhaps returning to the original creator, like JewelryAll) to ensure the custom elements are perfectly replicated.
Prevention is always better than having to file a claim. Proper care and storage of your jewelry can prevent many common causes of loss and damage. Always remove your rings and bracelets before doing heavy manual labor, cleaning with harsh chemicals, or going to the gym. Have a designated, secure spot in your home to store your jewelry when you take it off at night. When traveling, never pack valuable jewelry in checked luggage. Always keep it in your carry-on bag or, better yet, wear it. Additionally, take your valuable pieces to a jeweler every six months for a professional cleaning and inspection. A jeweler can spot a loose prong before a diamond falls out, saving you from a devastating loss and a complicated insurance claim.
Another important topic in the realm of jewelry insurance is traveling with your valuables. Many people wonder if their jewelry is covered when they leave the country. Most specialized standalone jewelry policies offer worldwide coverage, meaning your items are protected whether you are at home in New York or on vacation in Paris. However, it is crucial to verify this with your specific provider before you travel. You should also check if your policy has any specific requirements for transporting high-value items across borders.
In conclusion, securing comprehensive jewelry insurance coverage for your valuable items is a necessary investment. From luxury watches to a simple, elegant personalized keepsake, these items deserve protection against the uncertainties of life. By understanding the limitations of standard home insurance, obtaining accurate appraisals, selecting the right standalone policy, and practicing proper jewelry care, you can ensure that your most treasured pieces are safeguarded for generations to come. Whether it is an engagement ring symbolizing your future or a custom necklace celebrating your past, the peace of mind that comes with proper insurance is truly invaluable.
Why does personalized keepsake matter for readers?
A personalized keepsake matters because it transcends standard fashion; it represents a tangible memory, a unique design, or a deeply emotional bond. Because custom-made items—like an engraved ring or a name necklace—cannot simply be repurchased off a store shelf, protecting them with specialized insurance is vital. Having the right coverage guarantees that if the worst happens, you have the financial means to recreate that exact custom piece. For general readers, understanding this protection means gaining absolute peace of mind, knowing their most cherished, customized gifts and lifelong investments are fully safeguarded against life’s unpredictable moments.
Frequently Asked Questions
What is personalized keepsake in relation to A overview to jewelry insurance coverage for valuable items ??
In terms of jewelry insurance, a personalized keepsake is a custom-designed piece—like an engraved necklace or name ring—that holds unique emotional value. Insuring it ensures you are financially protected to precisely recreate this irreplaceable, one-of-a-kind treasure if it is ever lost, stolen, or damaged.

About author